Pag-IBIG Calamity Loan: How to Apply, Eligibility, Requirements, and Loan Amount
Your regular Pag-IBIG membership gives you access to emergency assistance through the Pag-IBIG Calamity Loan—a special program designed specifically for members affected by declared calamities.
This guide explains what the Pag-IBIG Calamity Loan is, who qualifies, how to apply, what you need, and how much you can borrow.
What Is a Pag-IBIG Calamity Loan
A Pag-IBIG Calamity Loan is emergency financial assistance available to Pag-IBIG members who are affected by a declared calamity. When the government declares a natural disaster or major emergency, Pag-IBIG opens this special loan program temporarily to help affected members with immediate financial needs.
The calamity loan is not the same as your regular Pag-IBIG loans. It is a separate program with different eligibility criteria and specific conditions tied to the calamity declaration.
The key distinction is timing: regular Pag-IBIG loans operate year-round, but calamity loans exist only when Pag-IBIG declares them in response to specific disasters.
When Calamity Loans Are Available
Pag-IBIG opens calamity loan programs in response to declared calamities. These have included typhoons, earthquakes, floods, fires, volcanic eruptions, and other major disasters affecting Filipinos. When a calamity occurs and is officially declared, Pag-IBIG announces the calamity loan program, specifies which areas are covered, and sets a deadline for applications.
Each calamity loan program is temporary. Pag-IBIG typically allows 90 days from calamity declaration for members to apply. The exact deadline is specified in each calamity loan announcement.
You cannot apply for a calamity loan if no calamity loan program is currently active. If disaster strikes during a period when no calamity loan is declared, your options are limited to regular Pag-IBIG loans or other sources of emergency funding.
Who Qualifies for a Calamity Loan
Generally, Pag-IBIG members who are affected by the declared calamity and meet the eligibility criteria can apply. However, specific eligibility rules vary depending on the calamity and Pag-IBIG’s response program.
Core Requirements
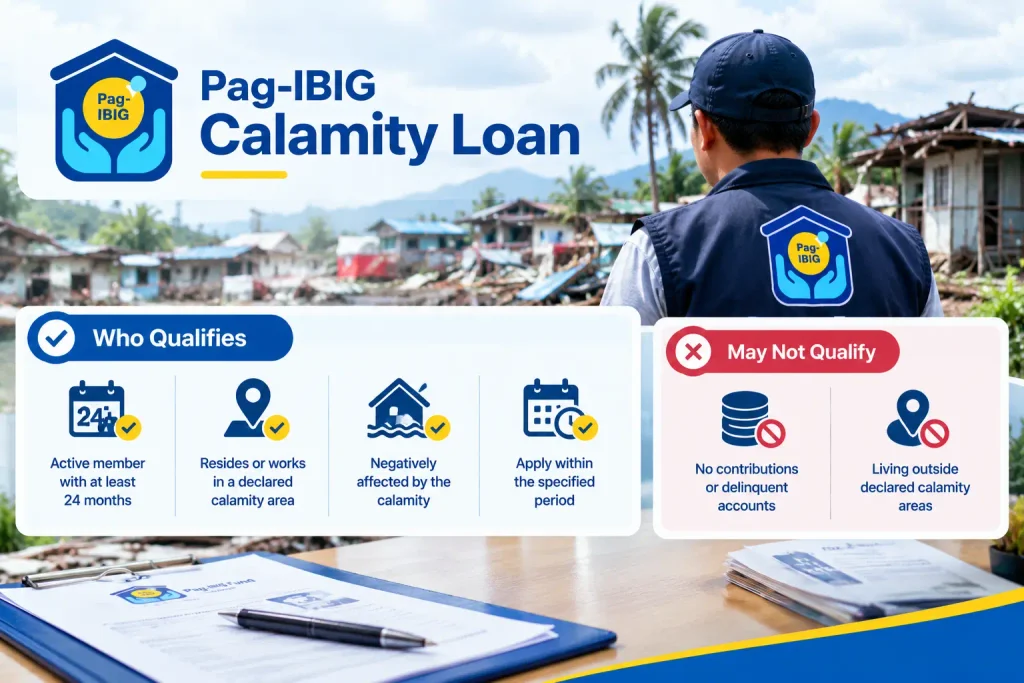
You must be an active Pag-IBIG member with at least 24 months of savings/contributions. You must reside or work in one of the declared calamity-affected areas. You must demonstrate that you were negatively affected by the calamity (damaged property, lost livelihood, displacement, etc.). You must apply within the specified availability period (typically 90 days from calamity declaration).
Who May Not Qualify
Members with no contributions or delinquent accounts may be ineligible. Members living outside declared calamity areas do not qualify.
The specific rules depend on each calamity loan program announcement. Always check the official Pag-IBIG announcement for your specific situation.
How Much You Can Borrow
Pag-IBIG sets a maximum loanable amount for calamity loans, though the exact amount varies depending on the specific calamity loan program and your membership status.
The amount you can actually borrow depends on multiple factors: your Total Accumulated Value (contributions plus dividends), your current loan obligations, your income, and the program’s maximum limit for that specific calamity.
You cannot borrow more than Pag-IBIG allows for your situation. If you need more than the maximum, regular Pag-IBIG loans remain available as an alternative.
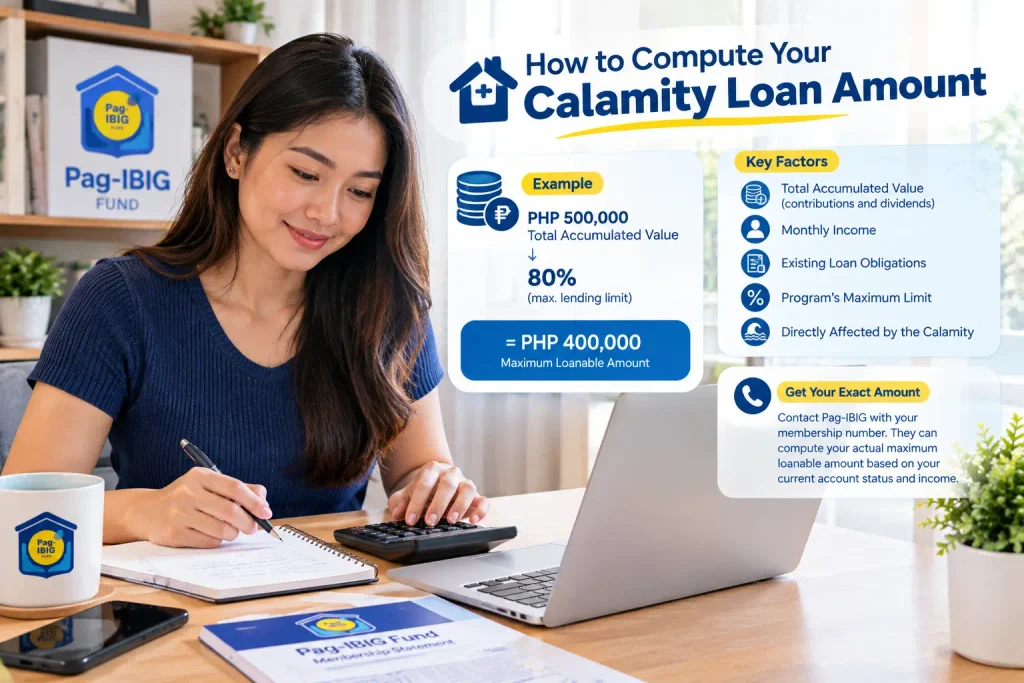
The loanable calamity loan amount is typically 80% of your Total Accumulated Value (contributions plus dividends). For example, if your accumulated value is PHP 500,000, you can borrow up to PHP 400,000 (80%). However, the actual approved amount also depends on your monthly income and capacity to repay.
For specific details on how much you can borrow for the current calamity loan program, contact Pag-IBIG or check the official announcement.
How to Apply for a Calamity Loan
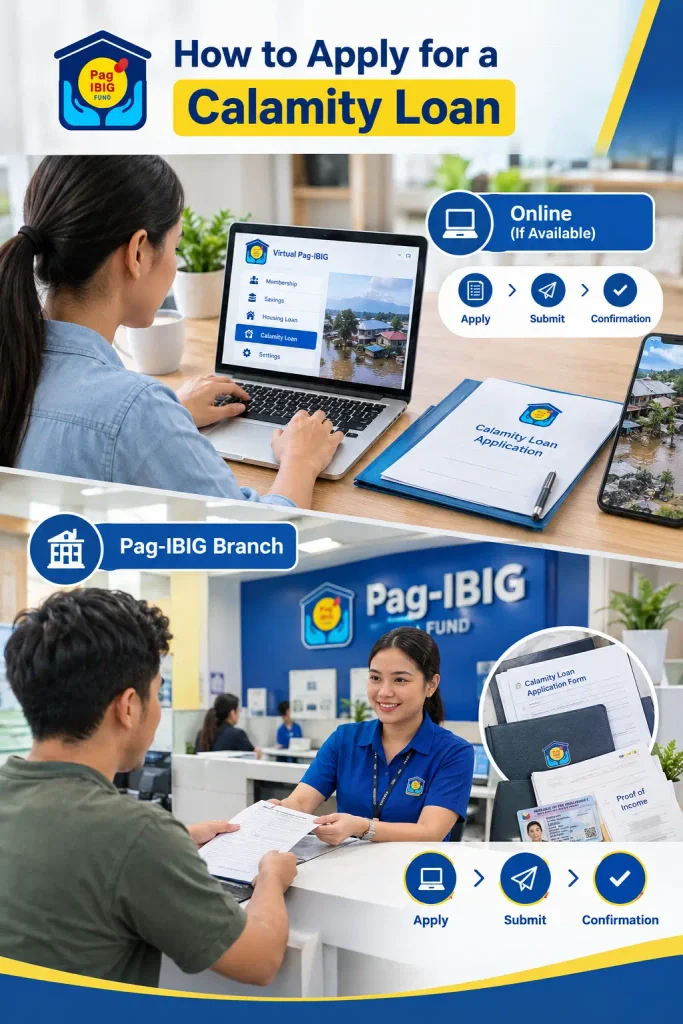
Applications are typically accepted through two channels: online via Virtual Pag-IBIG (if the program offers online application) or in person at Pag-IBIG branches.
Online Application (If Available)
Log into Virtual Pag-IBIG. Find the calamity loan application section. Complete the online application form with your membership details, proof of residency in the affected area, and documentation of damage or loss. Submit. You receive confirmation of application receipt. Processing begins.
Branch Application
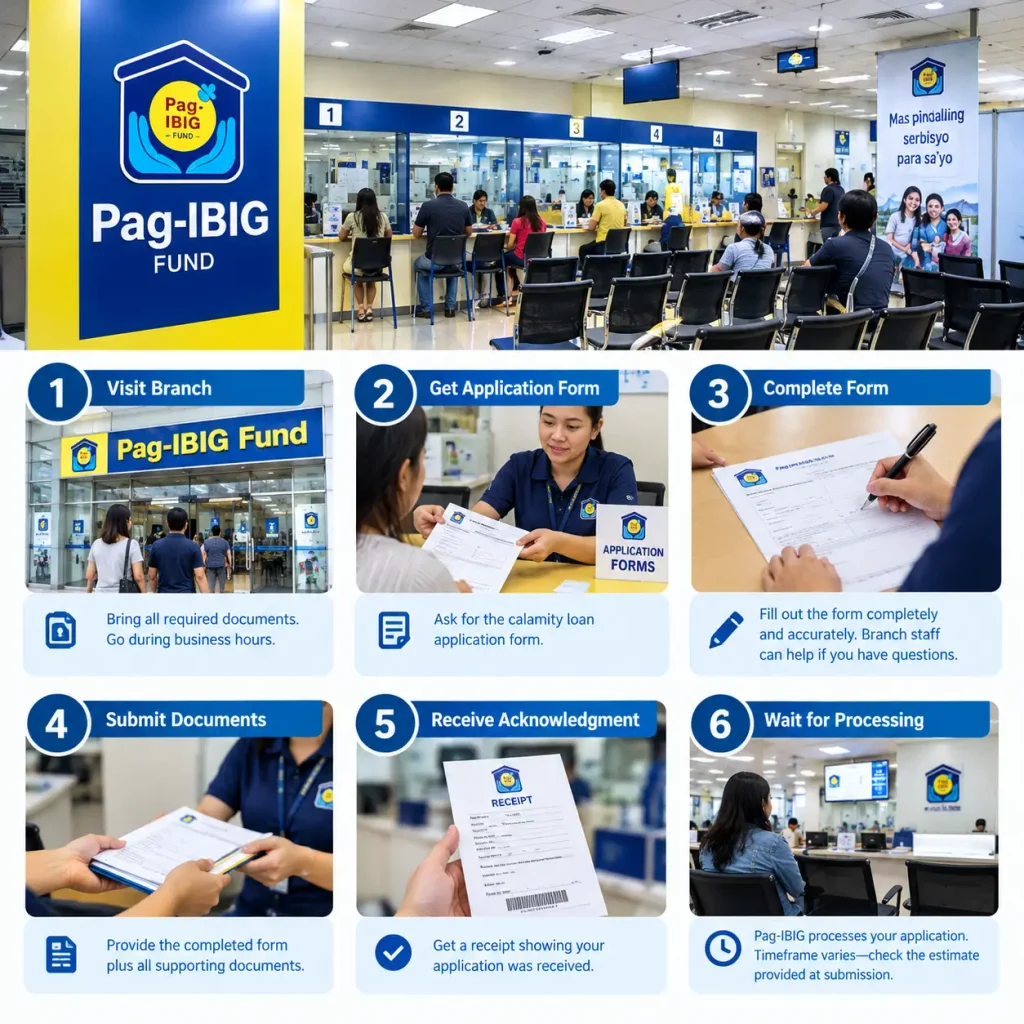
Visit a Pag-IBIG branch with required documents. Request a calamity loan application form. Complete the form with assistance from branch staff if needed. Submit with supporting documents. Receive acknowledgment of receipt. Processing begins.
Which Method to Choose
Online is faster if you have all documents digitally ready. Branch application is helpful if you have questions or need guidance. Both methods lead to the same evaluation process.
Requirements for Calamity Loan Application
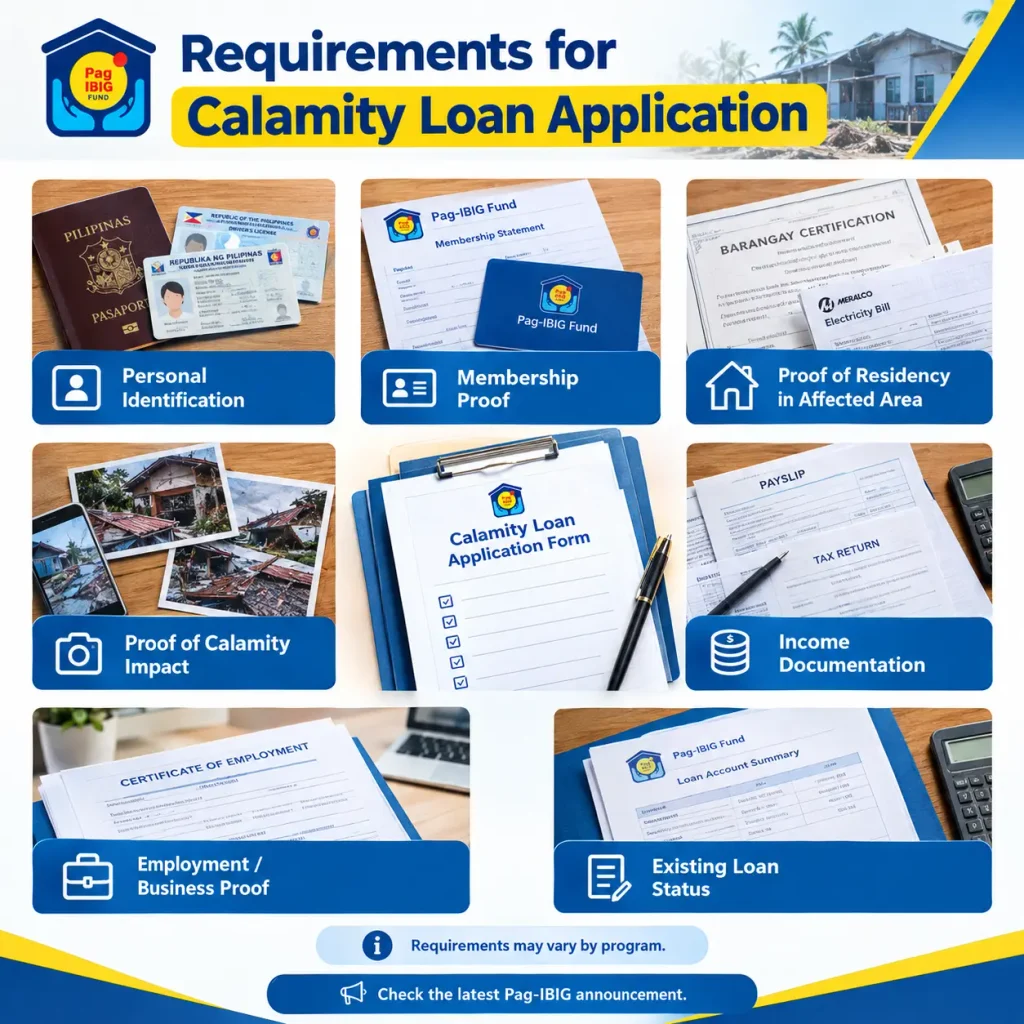
Requirements vary depending on the specific calamity loan program, but generally include:
Personal Identification
Valid government ID (passport, national ID, driver’s license, or other official ID)
Membership Proof
Pag-IBIG membership number and proof of membership (contribution slip, membership card, or account statement)
Proof of Residency in Affected Area
Government-issued ID showing address in declared calamity area, or barangay certification, utility bills, or other official documents showing residence
Proof of Calamity Impact
Photographs of damaged property, insurance report, barangay disaster certification, or other documentation showing damage or loss from the calamity
Income Documentation
Payslips, tax returns, certificate of self-employment income, or proof of income showing your current financial status
Employment Verification
For employed members: company certification of employment and salary. For self-employed: proof of business operation.
Existing Loan Status
Documentation of any existing Pag-IBIG loans to determine remaining borrowing capacity
Some programs may require additional documentation. Check the calamity loan announcement for complete requirements for your specific situation.
Interest Rate and Terms
The Pag-IBIG Calamity Loan carries an interest rate of 5.95% per annum. The loan may be payable over 2 or 3 years, with a 3-month grace period, subject to the applicable Pag-IBIG terms.
Monthly payments are deducted from your salary or paid directly to Pag-IBIG depending on your situation.
The specific terms and any variations depend on the calamity loan program announced by Pag-IBIG at the time.
Processing and Approval Timeline
Processing times vary depending on application volume and the calamity situation. Pag-IBIG prioritizes calamity loans because of their emergency nature, but processing still requires verification and underwriting.
General Timeline
Processing requires verification and underwriting of your application and supporting documents. Incomplete applications require resubmission and delay approval. Once approved, disbursement follows based on your chosen payment method.
Speeding Up Processing
Submit complete applications with all required documents. Follow up with Pag-IBIG to verify receipt and status. Respond promptly to any requests for additional information. Contact your branch or use online inquiry if processing takes longer than expected.
Avoid delays by submitting accurate, complete documentation from the start.
How to Compute Your Calamity Loan Amount
Computing your calamity loan is straightforward once you understand the formula Pag-IBIG uses.
Basic Computation
Most calamity loan programs base your loanable amount on a percentage of your Total Accumulated Value (your contributions plus accumulated dividends). For example, if you have PHP 500,000 accumulated and the program allows lending up to 80% of accumulated value, your maximum would be PHP 400,000.
However, your actual approved amount also depends on your income and capacity to repay. Pag-IBIG will not approve a loan payment that exceeds what your income can sustain.
Factors That Affect Your Amount
Your Total Accumulated Value (contributions and dividends). Your monthly income. Your existing Pag-IBIG loan obligations. The program’s maximum lending limit. Whether you were directly affected by the calamity.
Contact Pag-IBIG for Your Exact Amount
Rather than guessing, contact Pag-IBIG with your membership number. They can calculate your exact maximum loanable amount based on your current account status and income. This gives you certainty before applying.
Repayment of Calamity Loans
Once approved, you must repay your calamity loan according to Pag-IBIG’s terms.
Repayment Methods: Automatic payroll deduction (if employed). Over-the-counter payment at Pag-IBIG branches. Online banking transfer. Check payment. The method you choose may be limited based on the calamity loan program terms.
Payment Schedule: Pag-IBIG specifies your payment schedule Your first payment due date is specified in your loan agreement. Make payments on time to avoid penalties and maintain your Pag-IBIG standing.
Early Repayment: Confirm with Pag-IBIG whether your specific calamity loan allows penalty-free early payment.
Non-Payment Consequences: Late or missed payments result in penalties and may affect your Pag-IBIG account status. If facing hardship in making payments, communicate with Pag-IBIG immediately to discuss possible solutions or restructuring.
Calamity Loan vs. Multi-Purpose Loan
Many members wonder whether to apply for a calamity loan or regular Multi-Purpose Loan (MPL) when both are available.
Calamity Loan: Available only during declared calamities. Interest rate: 5.95% per annum, 2-year term. Focused on disaster recovery. Tied to affected areas. Limited application deadline (typically 90 days).
Multi-Purpose Loan: Available year-round. Standard interest rates and terms vary. Any personal or household purpose. Available to any member regardless of location. No application deadline—apply anytime.
If a calamity is declared and affects your area: you may apply for a calamity loan if you meet eligibility criteria. If no calamity loan is active: use regular Multi-Purpose Loans. If you need funds urgently for non-calamity purposes: use Multi-Purpose Loans immediately.
Typically yes—you can have an active multi-purpose loan and still apply for a calamity loan if one is declared. However, your total outstanding borrowing is capped, and having an existing MPL reduces your borrowing capacity for a calamity loan.
Documents to Bring or Submit
Before applying, gather and prepare all necessary documents to avoid delays or rejection.
Original Documents: Valid government ID. Pag-IBIG membership card or proof of membership. Proof of residency (utility bill, barangay certification, or ID showing affected-area address).
Supporting Documentation: Recent payslips (for employed) or tax returns/income certificate (for self-employed). Documentation of calamity impact (photos, barangay disaster certification, insurance report). Employment verification letter (if employed). Bank details for direct deposit (optional but recommended).
For Specific Situations: If you have existing Pag-IBIG loans: bring recent statements showing loan balance. If applying for a family member: authorization letter and relationship proof. If registering a complaint: supporting evidence and correspondence.
Document Checklist: Before submitting, verify you have every required document. Missing even one can delay approval or result in rejection. If unsure, contact Pag-IBIG to confirm your specific document needs for the current calamity program.
Online Application Process (If Available)
Some calamity loan programs may offer online application through Virtual Pag-IBIG, though this is not guaranteed for all calamities. Check the official calamity loan announcement to confirm whether online application is available for your specific disaster.
If online application is available, the typical process involves accessing Virtual Pag-IBIG, completing the calamity loan application form, uploading required documents, and submitting your application. Confirm exact procedures with Pag-IBIG as processes may vary by calamity and program.
Branch Application Process
If applying in person at a Pag-IBIG branch:
Visit Branch
Bring all required documents. Go during business hours.
Get Application Form
Ask for the calamity loan application form
Complete Form
Fill out the form completely and accurately. Illegible or incomplete applications cause delays. Branch staff can help if you have questions.
Submit Documents
Provide the completed form plus all supporting documents.
Receive Acknowledgment
Get a receipt showing your application was received. The receipt may have your application number for future status checking.
Wait for Processing
Pag-IBIG processes your application. Timeframe varies—check the estimate provided at submission.
Important Tips for Calamity Loan Success
Apply Immediately
Do not delay. The sooner you apply after the program opens, the sooner processing can begin. High volume after major calamities means delays for late applicants.
Keep Your Contact Information Current
Ensure Pag-IBIG has your correct phone number and email. This is how they contact you about your status.
Follow Up Appropriately
Check status after a few days to confirm receipt. Do not call daily. If processing takes longer than announced, then follow up.
Communicate Problems Immediately
If you face unique circumstances, explain to Pag-IBIG instead of just declining.
Whether online or branch, keep your application receipt, confirmation number, or acknowledgment. This proves you applied before the deadline if disputes arise.
What Happens After Approval
Once your calamity loan is approved, here is what comes next:
Loan Agreement: Pag-IBIG provides your loan agreement specifying the amount approved, interest rate, payment term, and monthly payment due. Read this carefully and keep it for your records.
Disbursement Notification: Pag-IBIG notifies you when funds will be released and how they will be disbursed (bank transfer, check, or cash).
Repayment Obligation Begins: Your first payment is due on the date specified in your loan agreement. Ensure you have this date and prepare to make timely payments.
Keep Loan Documents: Store your loan agreement and all disbursement documentation safely. You will need this if questions arise about your loan.
Through Virtual Pag-IBIG: Log in and look for calamity loan inquiry section. Enter your application number or membership details. The status displays showing whether your application is pending, approved, rejected, or processed.
By Calling Pag-IBIG: Contact the Pag-IBIG hotline or branch directly. Provide your membership number and application details. Staff can check your status and explain any delays.
In Person at Branch: Visit your nearest Pag-IBIG branch with your ID and membership number. Request status of your calamity loan application. Staff can provide immediate information and answer questions.
Frequency of Checking: Check after a few days to confirm receipt. Check weekly if processing is taking longer than announced timelines. Do not check obsessively—patience is needed during high-volume periods after major calamities.
Disbursement Methods
Once your calamity loan is approved, Pag-IBIG disburses the funds through available methods.
Direct Deposit to Bank Account: If you provide banking details, Pag-IBIG deposits approved funds directly to your designated bank account. Direct deposit typically processes faster than other methods.
Check Release: Pag-IBIG issues a check that you can claim at the branch. You must collect the check and deposit or cash it yourself.
Cash Disbursement at Branch: For smaller amounts, Pag-IBIG may release cash directly at the branch.
Online Payment: Some programs enable fund transfer through online banking or fund transfer services.
Calamity Loan vs. Regular Pag-IBIG Loans
Calamity loans and regular Pag-IBIG loans serve different purposes and have different mechanics.
Calamity Loans
Available only during declared calamity periods. Faster approval and disbursement. Focused on emergency recovery from specific disasters. May have favorable interest rates as relief assistance. Application deadline limited to calamity period. Eligibility tied to calamity-affected areas and impact verification.
Regular Pag-IBIG Loans
Available year-round. Standard approval timeline. Available for any purpose within loan program guidelines. Standard interest rates. No application deadline—available any time you need. Eligibility based on membership status and contribution history, not disaster affectation.
When to Use Each
During a declared calamity in your area: apply for calamity loan. Outside calamity declaration period or for non-calamity needs: use regular Pag-IBIG loans. If you need funds urgently but no calamity loan is declared: regular Pag-IBIG loans are your option.
Frequently Asked Questions
Conclusion
Pag-IBIG Calamity Loans exist to help members recover quickly when disaster strikes. When a calamity is declared affecting your area. The key is to apply quickly after the program is announced, submit complete documentation, and maintain communication with Pag-IBIG throughout the process.
Calamity loans are temporary programs tied to specific disasters. If you are affected by a declared calamity, treat the application deadline seriously—once it passes, you cannot apply for that specific disaster. Act fast, gather required documents, and get relief funds flowing to support your recovery.