Pag-IBIG MP2 Savings: How to Enroll, Check Balance, Earn Dividends, and Withdraw
You contribute to Pag-IBIG every month through payroll or voluntary payments. That money accumulates, but you want it to grow faster. You want to set aside extra money for savings specifically, earning better returns than regular contributions. You hear about MP2—the Modified Pag-IBIG II savings program—but are unsure what it is, whether you qualify, or how to enroll.
MP2 is your answer. It is a voluntary savings program for Pag-IBIG members who want to build accelerated wealth. Separate from your regular contributions, MP2 lets you save whatever you can afford each month and earn dividends typically higher than regular Pag-IBIG returns.
For members planning major life purchases, building emergency funds, or simply wanting their money to grow faster, MP2 transforms spare income into meaningful savings.
What Is Pag-IBIG MP2 Savings
Modified Pag-IBIG II (MP2) is a voluntary savings program separate from your regular Pag-IBIG membership contributions. It lets members save additional money beyond mandatory or voluntary regular contributions and earn annual dividends on those savings.
MP2 is not a replacement for regular contributions—it is an addition to them. Your regular contributions remain mandatory (for employees) or voluntary (for self-employed). MP2 is entirely optional and purely a savings choice. Members who enroll in MP2 maintain both their regular contribution account and their separate MP2 savings account.
The key distinction is purpose: regular contributions build your loan eligibility and membership benefits; MP2 is targeted savings designed purely for wealth accumulation. Pag-IBIG declares annual MP2 dividend rates, which have historically been competitive compared to traditional savings accounts and bank interest rates.
Who Can Enroll in Pag-IBIG MP2
Any active Pag-IBIG member can enroll in MP2. You do not need a minimum contribution history, specific employment status, or special approval. If you have a Pag-IBIG MID number and are in good standing (no delinquencies), you are eligible.
Eligible Pag-IBIG I members can enroll in MP2 once they meet the applicable enrollment requirements. Members who have been with Pag-IBIG for years can enroll anytime. Employed members, self-employed members, OFWs, and all other membership categories qualify equally.
How to Enroll in Pag-IBIG MP2
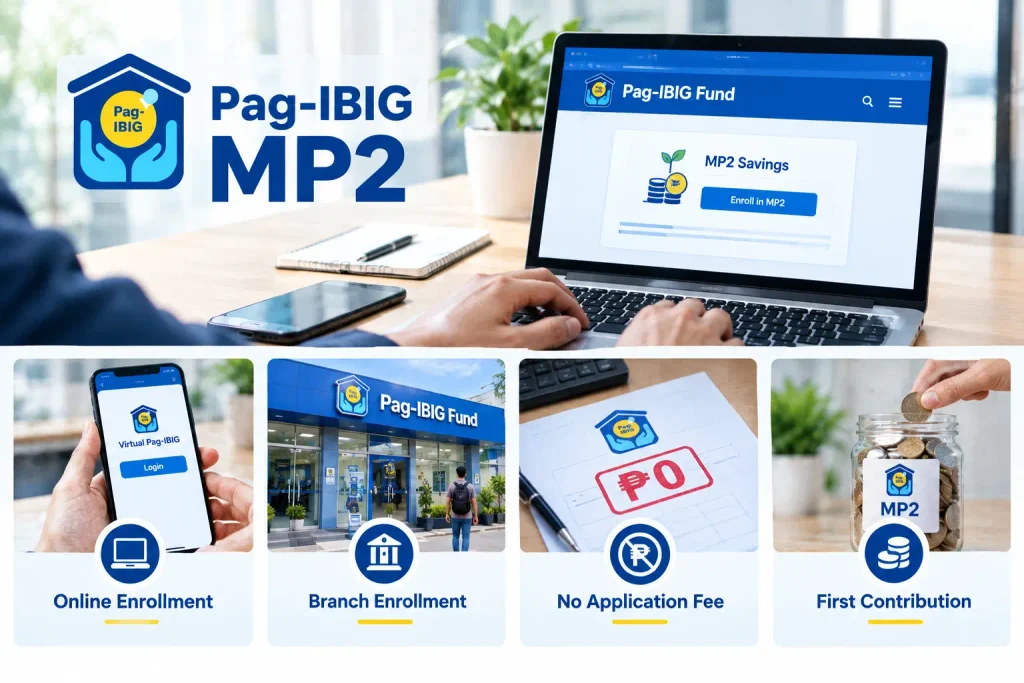
Enrollment is simple and can be done entirely online or at a branch.
Online Enrollment Through Virtual Pag-IBIG:
Log into your Virtual Pag-IBIG account. Find the MP2 section or savings programs area. Select “Enroll in MP2” or similar option. The system guides you through a brief enrollment form asking for basic information. Complete the form and submit. Confirmation appears immediately or within hours. You are now enrolled.
Branch Enrollment:
Visit any Pag-IBIG branch with your government ID and MID number. Ask staff about MP2 enrollment. Complete the MP2 enrollment form with assistance from branch staff. Submit, and you are enrolled same-day.
No Application Fee:
Enrollment is free. Pag-IBIG charges no application fee, processing fee, or enrollment cost for MP2.
Starting Your First Contribution:
After enrollment, you can make your first contribution immediately through any available payment channel. You do not need to wait for confirmation documents.
How Much You Contribute to MP2
You control your contribution amount with flexibility built in. There is a minimum contribution requirement of PHP 500, though specific amounts and any maximum limits may vary based on your membership category.
Flexible Contributions:
You can contribute monthly, lump sum, or whenever you have extra funds. The flexibility lets you align contributions with your cash flow.
Payment Methods:
Pay MP2 contributions through the same channels as regular Pag-IBIG contributions: online banking, authorized banks, Bayad Centers, GCash, or direct branch payment.
Automatic Deduction:
You can set up automatic monthly MP2 contributions through your bank’s recurring payment feature. This ensures consistent savings without remembering to pay each month.
Checking Your MP2 Savings Balance Online
Through Virtual Pag-IBIG: Log into your account. Navigate to MP2 section or savings programs area. Your MP2 balance displays showing total contributions and earned dividends. You can see your payment history, contribution dates, amounts, and year-to-date accumulated value.
Contribution History: The MP2 section shows each contribution posted, when it posted, and the current balance. Gaps indicate months you did not contribute (which is fine—contributions are voluntary).
Dividend Tracking: You can view dividends earned in the current year and accumulated dividends from previous years, showing exactly how your money is working for you.
No Delays: MP2 contributions you make directly are processed through Pag-IBIG systems. You can verify posting in your Virtual Pag-IBIG account after a processing period.
Understanding Pag-IBIG MP2 Dividends
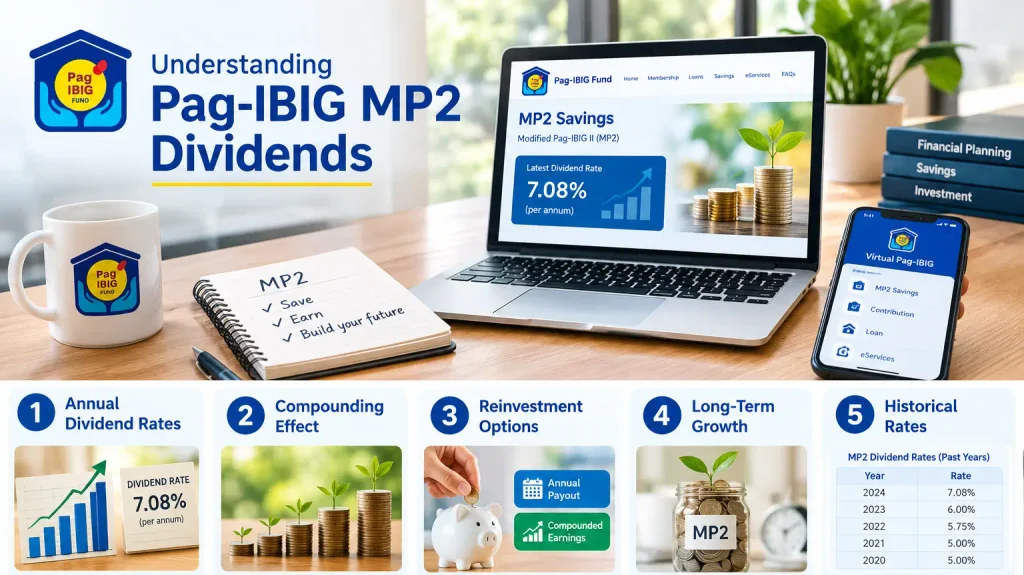
Pag-IBIG declares annual MP2 dividend rates based on fund performance. These rates are applied to your accumulated MP2 balance each year.
How Dividends Work:
Each year Pag-IBIG announces the MP2 dividend rate for that year. This rate is applied to your accumulated MP2 savings balance. The specific timing and calculation method for dividend application follows Pag-IBIG’s official procedures.
Compounding Effect:
Dividends earned in year one are added to your principal. In year two, you earn dividends on both your original contributions and the prior year’s dividends. This compounding significantly accelerates savings over decades.
Reinvestment:
Dividends are added to your balance and contribute to future earning potential. Members may choose annual dividend payout or compounded dividend earnings, subject to Pag-IBIG Fund rules.
Long-Term Impact:
Over decades of consistent MP2 contributions, your savings accumulate with the benefit of declared dividends. The total growth depends on contribution amounts, frequency, and dividend rates declared by Pag-IBIG.
Historical Rates:
MP2 dividend rates have varied by year based on fund performance. Members should assume future dividend rates are not guaranteed but can review historical rates to understand typical ranges.
Withdrawal and Claiming MP2 Savings
MP2 savings belong to you. The specific withdrawal conditions and eligibility depend on your membership status and the current Pag-IBIG MP2 program rules.
Claiming Your Savings: When you qualify for withdrawal, contact your nearest Pag-IBIG branch with your MID, government ID, and supporting documentation. Branch staff guide you through the claim application. Processing and disbursement follow standard procedures.
Important MP2 Considerations
Separate From Regular Contributions: MP2 is completely separate from your regular Pag-IBIG contributions. They are tracked in different accounts, earn different dividend rates, and can have different withdrawal timelines. Do not confuse one with the other when checking your balance.
Voluntary Nature: Unlike regular contributions which are mandatory for employees, MP2 is entirely voluntary. You decide whether to enroll, how much to contribute, and when to contribute. There is no penalty for not enrolling, and you can discontinue contributions anytime without penalty.
Membership Status: Maintain good standing with your Pag-IBIG membership to keep your MP2 account in active status. If there are issues with your membership, contact Pag-IBIG to understand how this affects your MP2 account.
Funds Remain Protected: MP2 savings belong entirely to you and are protected under Pag-IBIG regulations. These are not company investments or third-party accounts—they are your personal savings held in trust by Pag-IBIG.
Payment Methods for MP2 Contributions
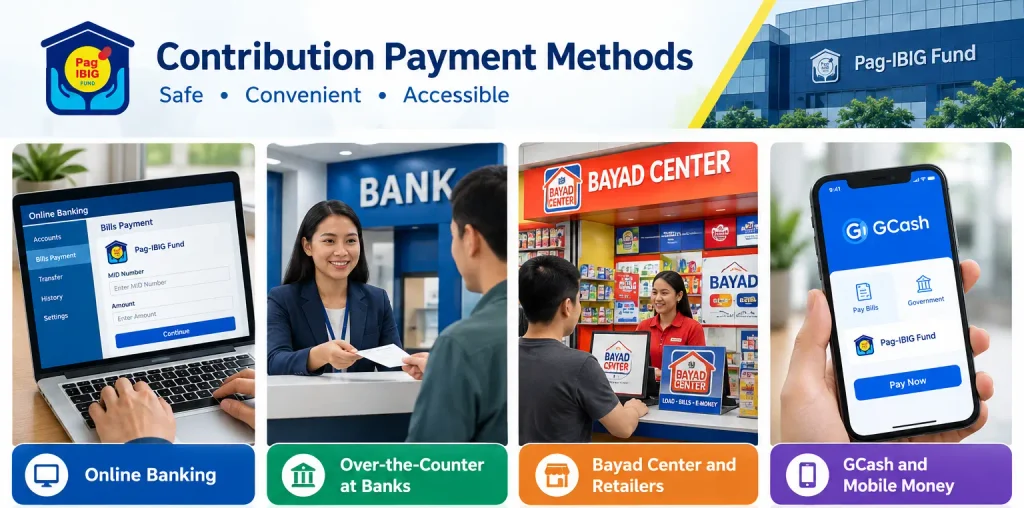
Online Banking:
Log into your bank’s online platform, select Pag-IBIG MP2 payment, enter your MID and amount, and complete the transaction.
Over-the-Counter at Banks:
Visit any partner bank with your MID and desired amount. Bank staff process the payment, and funds reach Pag-IBIG within days.
Bayad Center and Retailers:
Authorized payment centers throughout the Philippines accept MP2 payments. Visit any location with your MID and pay your contribution amount.
GCash and Mobile Money:
Some platforms accept MP2 contributions. Check current availability with your service provider.
Automatic Bank Transfers:
Set up recurring automatic transfers through your bank’s online system. This ensures consistent monthly contributions without remembering to pay.
Best Practices for MP2 Savings
Consistency Matters:
Set up automatic monthly contributions at whatever amount you can afford. Consistency builds wealth faster than sporadic large contributions. Even PHP 1,000 monthly compounds significantly over decades.
Regular Balance Checks: Log into Virtual Pag-IBIG monthly to verify your contributions posted and dividends are accruing. This habit keeps you engaged with your savings progress.
Plan Contribution Timing: If you receive annual bonuses or seasonal income increases, allocate portions to MP2. Using bonus money prevents disrupting regular budget while accelerating savings.
Understand Your Goal: Know why you are saving in MP2—whether for a home purchase, education funding, emergency reserves, or retirement. This clarity helps you maintain consistency and determine how much to contribute.
Keep Documentation: Save screenshots or printed statements of your MP2 balance periodically. Having your own records helps if questions arise and provides personal satisfaction tracking progress.
Why Members Choose MP2 Over Regular Savings
Members often ask why MP2 is better than simply saving money in a bank account.
Competitive Dividend Rates
MP2 dividend rates have historically been comparable to or better than bank savings account interest rates. Your money grows faster than in many traditional savings accounts.
Government-Backed Security
Your MP2 savings are held in trust by Pag-IBIG, a government agency. This official status provides security and protection many members value compared to private financial institutions.
Forced Savings Discipline
Knowing your money is in an official government account makes it harder to spend impulsively. MP2 creates a psychological barrier that encourages savings discipline many members struggle to achieve independently.
Common MP2 Enrollment Mistakes
Confusing MP2 With Regular Contributions: MP2 is separate and optional. You must enroll specifically for MP2.
Not Understanding Flexibility: MP2 contributions are completely flexible. Contribute PHP 500 one month, PHP 10,000 the next, or skip a month. No penalties.
Assuming Automatic Enrollment: New Pag-IBIG members are not automatically enrolled in MP2. You must actively enroll through Virtual Pag-IBIG or a branch.
Underestimating Impact: PHP 500 monthly over 30 years compounds into substantial savings. Do not underestimate small consistent contributions.
Smart Contribution Strategies
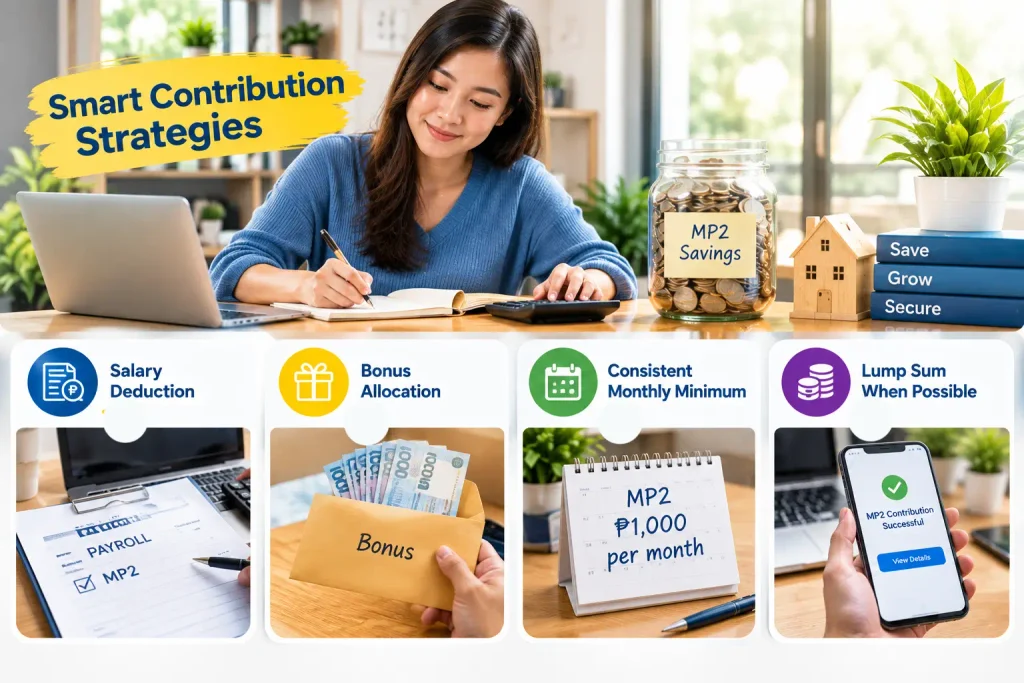
Salary Deduction:
Ask your HR whether they can deduct MP2 contributions directly from your paycheck as an available option. If available, this makes savings automatic.
Bonus Allocation:
When you receive annual bonuses, allocate 20-30% to MP2. This uses windfall income without affecting regular budget.
Consistent Monthly Minimum:
Set a monthly MP2 contribution you can maintain regardless of circumstances. Even PHP 1,000 monthly becomes PHP 12,000 yearly, compounding over time.
Lump Sum When Possible:
When unexpected money arrives (tax refund, inheritance), make a lump-sum MP2 contribution. This accelerates your savings trajectory.
Planning Long-Term MP2 Success
Five-Year Target: Set a realistic five-year goal for your MP2 balance. Calculate monthly contributions needed to reach that goal, assuming conservative dividend rates.
Retirement Integration: Calculate how your accumulated MP2 plus regular contributions could provide as retirement income. This shows your total financial security trajectory.
Emergency Fund: Some members use MP2 as part of their savings strategy. Building savings in MP2 provides funds for future needs while earning dividends.
Major Purchase Planning: If planning a home or vehicle in 3-5 years, calculate backward from that need to determine MP2 contributions required.
Faqs
Conclusion
Pag-IBIG MP2 Savings is a powerful tool for members who want their savings to work harder. Unlike regular contributions tied to loan eligibility and membership benefits, MP2 is pure savings designed for wealth accumulation. The flexibility to contribute what you can afford, combined with competitive dividend rates and complete control over your money, makes MP2 attractive for members building emergency reserves, planning major purchases, or simply accelerating their path to financial security.